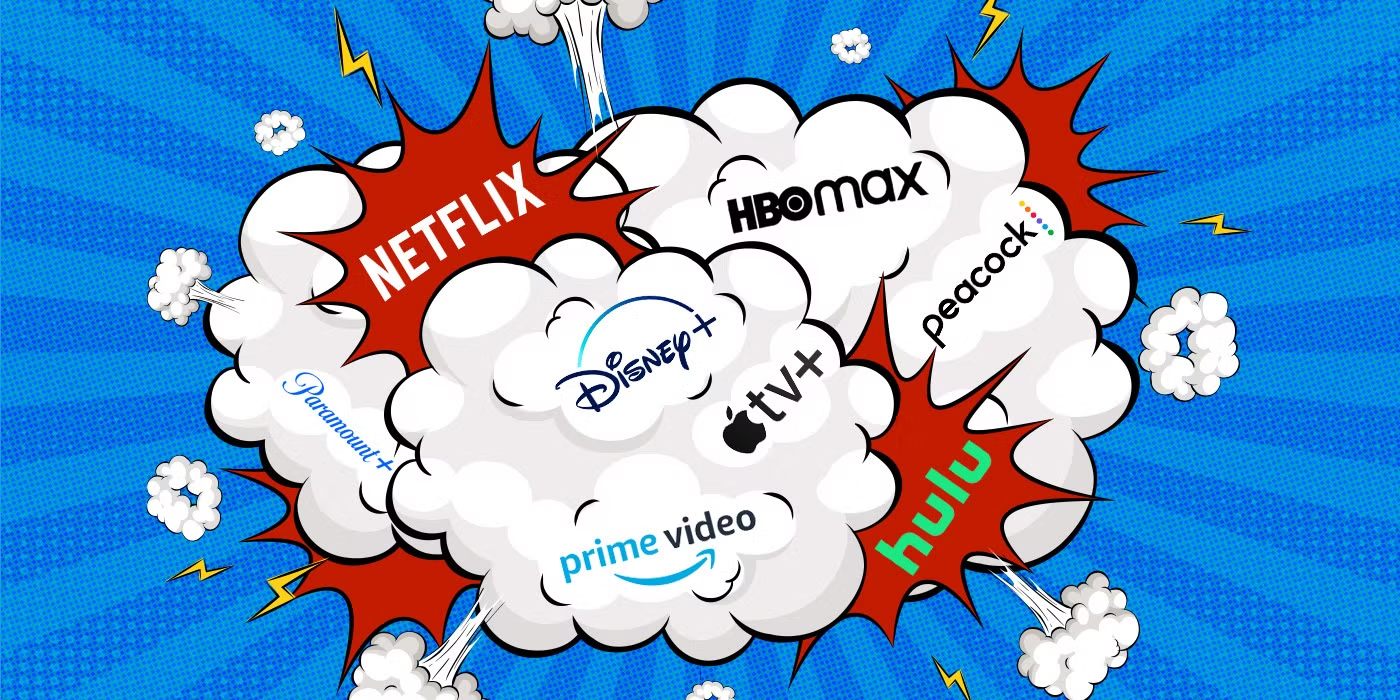
The streaming industry, once defined by rapid expansion and subsidized subscription costs, has entered a new era of maturity. The “Streaming Wars” have transitioned from a battle for raw subscriber numbers to a sophisticated struggle for average revenue per user (ARPU) and long-term retention. In this landscape, the “Big Three”—Netflix, Disney+, and Amazon Prime Video—face the dual challenge of rising production costs and consumer subscription fatigue. While these giants utilize massive scale and data analytics to maintain dominance, a secondary front has opened where niche platforms like Crunchyroll, Shudder, and Mubi are proving that specialized depth can be more valuable than generalized breadth.
The Dominance of the Streaming Giants: Netflix, Disney+, and Amazon
The top tier of the streaming hierarchy is occupied by companies with the capital to produce “tentpole” content—high-budget series and films designed to attract a global audience. However, the strategies employed by these leaders differ significantly based on their parent company’s core business model and historical strengths. Netflix remains the only “pure-play” streamer that relies primarily on its own content engine, while Disney and Amazon use streaming as a component of larger corporate ecosystems.
Netflix’s Data-Driven Content Engine
Netflix has pioneered the use of predictive analytics to determine which shows to greenlight. By analyzing billions of data points—including where users pause, when they abandon a series, and what genres they “binge”—Netflix creates a personalized content feed for over 260 million subscribers. Their strategy focuses on volume and variety, ensuring that there is always something new to watch, which helps mitigate the risk of a single high-profile failure. Recently, Netflix has shifted toward “spectacle” programming, investing heavily in global hits like Squid Game and Stranger Things to drive cultural relevance.
Disney+’s Intellectual Property Powerhouse
Disney+ entered the market with an unparalleled library of established Intellectual Property (IP). By leveraging brands such as Marvel, Star Wars, Pixar, and National Geographic, Disney was able to achieve record-breaking growth in its first two years. Their strategy is built on synergy; a streaming series often serves as a marketing vehicle for theme park attractions, merchandise, and theatrical sequels. However, Disney has recently faced “franchise fatigue,” leading to a strategic pivot toward higher quality control and a reduction in the sheer number of Marvel and Star Wars releases to maintain brand prestige.
Amazon Prime Video’s Ecosystem Advantage
Unlike its competitors, Amazon Prime Video does not need to be profitable as a standalone service. It functions as a “loss leader” to drive subscriptions to the broader Amazon Prime ecosystem. The primary goal is to increase customer loyalty to the Amazon retail platform; data shows that Prime Video users are more likely to spend more on the e-commerce site. This allows Amazon to make massive, high-risk bets, such as the billion-dollar investment in The Lord of the Rings: The Rings of Power, which serves as a prestige anchor for the service.

The Rise of Niche Platforms: Finding Success in Specialization
While the giants fight for the “average” viewer, niche platforms are flourishing by catering to “super-fans.” These services do not attempt to be the primary entertainment source for a household; instead, they position themselves as an essential “add-on” for enthusiasts of specific genres. This specialization creates a unique competitive advantage that protects them from the aggressive price-cutting of larger rivals.
Community and Curation over Algorithms
Niche platforms often prioritize human curation over algorithmic recommendations. For example, Mubi offers a hand-picked selection of independent and international cinema, often rotating titles in a “film-of-the-day” format. This creates a sense of exclusivity and discovery that automated feeds cannot replicate. By fostering a community through forums, reviews, and specialized events, these platforms build high levels of brand loyalty, leading to significantly lower churn rates (the percentage of subscribers who cancel) compared to generalist services.
Case Studies in Niche Dominance
Several platforms have successfully carved out profitable segments of the market by focusing on underserved audiences:
- Crunchyroll: Focusing exclusively on Anime, Crunchyroll has built a massive global audience by offering simulcasts directly from Japan. Their deep understanding of anime culture allows them to expand into merchandise and theatrical distributions.
- Shudder: Owned by AMC Networks, Shudder caters specifically to horror, thriller, and supernatural fiction fans. By commissioning original horror content and hosting “live” viewing events, they have become the go-to destination for the genre.
- BritBox: A joint venture between the BBC and ITV, this service targets fans of British television, offering a concentrated library of UK classics and procedurals that would otherwise be lost in the vast catalogs of Netflix or Hulu.

Strategic Shifts: Monetization, Bundling, and Ad-Tiers
The “Growth at All Costs” era has ended, replaced by a focus on “Sustainable Profitability.” This shift has led to several controversial but necessary changes in how streaming services operate. Consumers who once enjoyed ad-free experiences for low monthly fees are now navigating a landscape that increasingly resembles the cable television model they originally sought to escape.
The Return of the Ad-Supported Model
Netflix and Disney+ have both introduced “Ad-Supported Tiers.” This serves two purposes: it provides a lower entry price for price-sensitive consumers and creates a new, lucrative revenue stream through digital advertising. Interestingly, the revenue generated from ads plus the lower subscription fee often exceeds the revenue from a standard ad-free subscription. This “hybrid” model is becoming the industry standard as platforms seek to maximize the value of every viewer.
| Strategy | Primary Goal | Key Players |
|---|---|---|
| Ad-Supported Tiers | Increase ARPU & Accessibility | Netflix, Disney+, Hulu, Max |
| Password Sharing Crackdown | Convert Borrowers to Subscribers | Netflix, Disney+ |
| Content Licensing | Generate Immediate Cash Flow | Warner Bros. Discovery, Disney |
| Bundling | Reduce Churn & Increase Value | Disney/Hulu/ESPN+, Apple One |
Combating Churn and Subscription Fatigue
As households reach their limit on the number of active subscriptions, platforms are turning to “Bundling” to provide perceived value. Bundles, such as the Disney+/Hulu/ESPN+ package or the Paramount+ with Showtime offering, make it more difficult for users to cancel because they would lose access to multiple content types (e.g., live sports, kids’ programming, and prestige drama) simultaneously. Furthermore, platforms are increasingly returning to weekly release schedules for major shows to keep subscribers engaged over several months rather than allowing them to binge and cancel within 30 days.

The Future Outlook: Consolidation or Fragmentation?
The next phase of the streaming wars will likely be defined by consolidation. Smaller generalist platforms that lack the scale of Netflix or the ecosystem of Amazon may find it impossible to compete as content costs continue to rise. We are already seeing evidence of this through mergers and strategic partnerships, such as the formation of Warner Bros. Discovery (Max).
However, fragmentation will likely persist in the niche market. Because niche platforms operate on smaller budgets and have highly dedicated user bases, they are less susceptible to the “merger mania” affecting the larger players. The future of streaming is not a “winner-take-all” scenario, but rather a tiered ecosystem where a few “super-services” act as the foundation of home entertainment, supplemented by a rotating selection of specialized niche platforms that cater to the specific passions of the viewer.
Frequently Asked Questions (FAQ)
- Q1: Why are streaming services increasing prices while adding ads?
- Streaming services are shifting from a growth-focused model to a profitability-focused model. The cost of producing high-quality original content has skyrocketed, and platforms can no longer subsidize these costs with low subscription fees. Adding ads allows them to keep a lower-priced entry point for consumers while generating additional revenue from advertisers.
- Q2: Can niche platforms really survive against giants like Netflix?
- Yes, because they serve a different purpose. Niche platforms focus on “depth” rather than “breadth.” By catering to a specific community (like horror fans or anime enthusiasts), they build high loyalty and low churn. They don’t need 200 million subscribers to be profitable; they only need a few million dedicated fans who view the service as an essential hobby expense.
- Q3: What is “Subscription Fatigue” and how does it affect the market?
- Subscription fatigue occurs when consumers feel overwhelmed by the number of monthly payments and the difficulty of finding content across multiple apps. This leads to “churn and burn” behavior, where users subscribe for one month to watch a specific show and then immediately cancel. Platforms are fighting this through bundling and annual discount plans.
- Q4: Is the era of “Binge-Watching” ending?
- While Netflix still releases many shows all at once, many other platforms (Disney+, Max, Amazon) have moved back to weekly releases for their biggest hits. This “appointment viewing” helps keep the show in the cultural conversation for longer and prevents subscribers from canceling their service immediately after a weekend of bingeing.
- Q5: Will all streaming services eventually merge into one?
- It is unlikely that there will be only one service, but we will likely see more “aggregation.” This means you might access multiple services through a single interface (like Apple TV or Roku) or buy them in large bundles. The market is moving toward a structure that looks very similar to the old cable TV packages, but delivered over the internet.